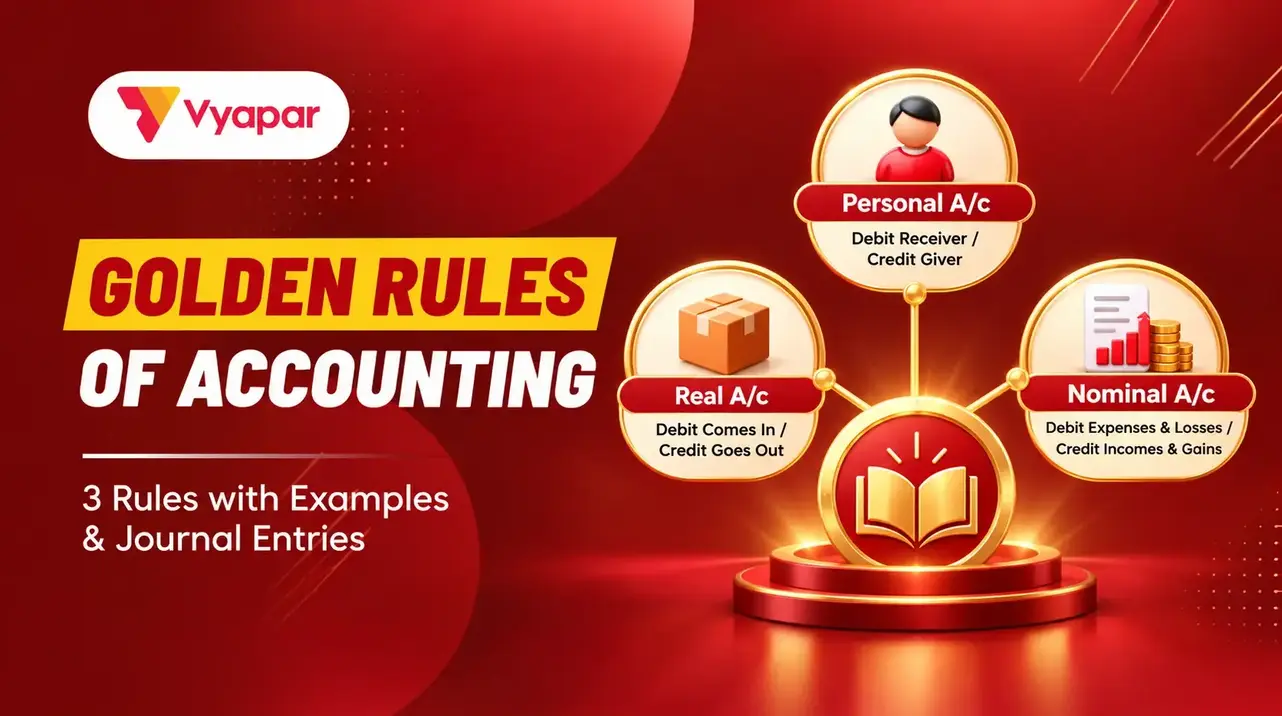
The 3 Golden Rules: They help decide which account to debit and which to credit.
Know the Account Types: Identify whether an account is Personal, Real, or Nominal before applying the rule.
Every Transaction Has Two Sides: Each transaction affects at least two accounts through debit and credit.
Apply Them to Daily Transactions: Sales, purchases, payments, and expenses all follow the same debit-credit logic.
GST Needs Separate Entries: GST collected and eligible input GST are recorded separately from sales and purchase values.
Avoid Common Accounting Mistakes: Keep business and personal transactions separate and record each transaction correctly.
Traditional vs Modern Accounting: Traditional accounting uses three account types, while modern accounting uses assets, liabilities, equity, income, and expenses.
Software Handles Entries Automatically: Accounting software records routine debit and credit entries in the background.
The golden rules of accounting help you understand which account to debit and which account to credit when recording a business transaction.
What Are the Golden Rules of Accounting?
The golden rules of accounting are three simple rules used to decide which account should be debited and which should be credited.
Every business transaction has two sides. For example, when you buy a computer for your shop and pay by bank, the computer comes into the business while money goes out of the bank.
The three golden rules are:
Account Type
Golden Rule
Personal Account
Debit the receiver, credit the giver
Real Account
Debit what comes in, credit what goes out
Nominal Account
Debit all expenses and losses, credit all incomes and gains
You can also refer to the ICAI accounting study material for the traditional classification of accounts and golden rules.
Types of Accounts in Accounting
Before applying the golden rules, you need to know which type of account you are dealing with.
1. Personal Account
Personal accounts are related to people, businesses, banks and other entities.
Customer account
Supplier account
Bank account
Company account
Capital account
Drawings account
Rule: Debit the receiver, credit the giver.
Example: You sell goods worth ₹30,000 to Ramesh on credit.
Account
Dr / Cr
Amount
Ramesh’s A/c
Dr
₹30,000
Sales A/c
Cr
₹30,000
Remember: If a person or business receives value, debit the receiver. If they give value, credit the giver.
2. Real Account
Real accounts are related to the assets owned by a business.
Cash
Furniture
Machinery
Vehicles
Computers
Buildings
Goodwill
Software and other intangible assets
Rule: Debit what comes in, credit what goes out.
For example, when you purchase a computer, the computer comes into the business, so the Computer Account is debited.
Account
Dr / Cr
Amount
Computer A/c
Dr
₹45,000
Cash A/c
Cr
₹45,000
Computer comes in → Debit Computer A/c
Cash goes out → Credit Cash A/c
3. Nominal Account
Nominal accounts record the income, expenses, gains and losses of a business.
Examples of expenses:
Rent
Salary
Electricity
Transport
Advertising
Examples of income and gains:
Sales
Commission received
Interest received
Profit on sale of an asset
Rule: Debit all expenses and losses, credit all incomes and gains.
For example, when you pay shop rent, the Rent Account is debited because it is an expense.
Account
Dr / Cr
Amount
Rent A/c
Dr
₹18,000
Bank A/c
Cr
₹18,000
Rent is an expense, so it is debited.
The 3 Golden Rules of Accounting
Rule 1: Debit the Receiver, Credit the Giver
This rule applies to personal accounts. When a person or business receives something, debit their account. When they give something, credit their account.
Rule 2: Debit What Comes In, Credit What Goes Out
This rule applies to real accounts. When an asset comes into the business, debit it. When an asset goes out, credit it.
Rule 3: Debit All Expenses and Losses, Credit All Incomes and Gains
This rule applies to nominal accounts. Expenses and losses are debited, while income and gains are credited.
Golden Rules of Accounting With Journal Entries
Here are some common transactions that small businesses deal with every day.
1. Started a business with ₹5,00,000 cash
Account
Dr / Cr
Amount
Cash A/c
Dr
₹5,00,000
Capital A/c
Cr
₹5,00,000
Cash comes into the business, so the Cash Account is debited. Capital represents the amount brought in by the owner.
2. Purchased goods worth ₹80,000 on credit
Account
Dr / Cr
Amount
Purchases A/c
Dr
₹80,000
Mehta Traders A/c
Cr
₹80,000
Purchases are debited, and the supplier’s account is credited.
3. Made a cash sale of ₹22,000
Account
Dr / Cr
Amount
Cash A/c
Dr
₹22,000
Sales A/c
Cr
₹22,000
Cash comes into the business, so the Cash Account is debited. Sales income is credited.
4. Paid staff salary of ₹35,000 by bank
Account
Dr / Cr
Amount
Salary A/c
Dr
₹35,000
Bank A/c
Cr
₹35,000
Salary is an expense, so it is debited. Money goes out of the bank, so the Bank Account is credited.
5. Bought a delivery van for ₹6,00,000 by cheque
Account
Dr / Cr
Amount
Delivery Van A/c
Dr
₹6,00,000
Bank A/c
Cr
₹6,00,000
The vehicle comes into the business, so it is debited. The bank balance goes down, so the Bank Account is credited.
A Simple Example From a Retail Shop
Let’s see how these rules work during a normal business day. Suppose Sunil runs a retail clothing shop
Transaction
Journal Entry
Bought clothes worth ₹40,000 in cash
Dr Purchases ₹40,000 / Cr Cash ₹40,000
Sold clothes worth ₹8,000 for cash
Dr Cash ₹8,000 / Cr Sales ₹8,000
Sold clothes worth ₹12,000 on credit
Dr Customer ₹12,000 / Cr Sales ₹12,000
Paid shop rent of ₹10,000
Dr Rent ₹10,000 / Cr Cash ₹10,000
Paid electricity bill of ₹2,500
Dr Electricity ₹2,500 / Cr Cash ₹2,500
Received ₹12,000 from the customer through UPI
Dr Bank ₹12,000 / Cr Customer ₹12,000
Took ₹3,000 from the business for personal use
Dr Drawings ₹3,000 / Cr Cash ₹3,000
The important thing is that every transaction has two sides. Once you understand what came in, what went out, who received or gave money, and whether it was income or an expense, identifying debit and credit becomes easier.
How do the Golden Rules Apply to GST?
GST transactions can look confusing at first because a single sale or purchase can involve multiple accounts.
GST on a Sale
Suppose you make a sale of ₹1,00,000 plus 18% GST. The customer pays ₹1,18,000.
Account
Dr / Cr
Amount
Customer A/c
Dr
₹1,18,000
Sales A/c
Cr
₹1,00,000
Output CGST A/c
Cr
₹9,000
Output SGST A/c
Cr
₹9,000
The ₹18,000 GST collected is not sales income. It is tax collected on behalf of the government.
GST on a Purchase
Suppose you purchase goods worth ₹50,000 plus 18% GST.
Account
Dr / Cr
Amount
Purchases A/c
Dr
₹50,000
Input CGST A/c
Dr
₹4,500
Input SGST A/c
Dr
₹4,500
Supplier A/c
Cr
₹59,000
Where eligible, the GST paid on purchases can be available as input tax credit. This is why eligible input GST should be recorded separately instead of simply adding it to the purchase value. Using GST billing software can make it easier to record GST separately and keep track of input and output tax.
Traditional vs Modern Accounting Rules
You may also come across a different way of explaining debit and credit.
Traditional approach
Modern approach
Personal, Real and Nominal accounts
Assets, Liabilities, Equity, Income and Expenses
Three golden rules
Debit and credit based on the type and movement of accounts
Commonly taught in traditional accounting education
Commonly used in modern accounting systems and software
The terminology is different, but both approaches help you arrive at the debit and credit entry.
If you are using accounting software, you may see the modern account categories more often.
Common Mistakes When Applying the Golden Rules
Treating every payment as an expense: Buying a computer or machine is not the same as paying electricity or rent. An asset purchase and a business expense are recorded differently.
Treating drawings as a business expense: If the owner takes ₹10,000 from the business for personal use, it is a drawing, not a business expense.
Mixing personal and business transactions: Try to keep personal spending separate from business transactions. It makes your books much easier to understand.
Recording credit sales only when payment is received: A credit sale is recorded when the sale happens, not only when the customer pays.
Creating duplicate ledgers: If you create separate ledgers for the same customer or supplier, their outstanding balance can become difficult to track.
Adding eligible input GST to the purchase cost: Where input tax credit is available, keep the input GST separate from the purchase value.
You don’t always have to manually write every debit and credit entry.
When you create a transaction in accounting software, the software records the corresponding accounts in the background.
What you do
Accounts recorded
Create a sales invoice
Customer Dr / Sales Cr / Output GST Cr
Record payment received
Cash or Bank Dr / Customer Cr
Enter a purchase
Purchase Dr / Input GST Dr / Supplier Cr
Record an expense
Expense Dr / Cash or Bank Cr
Record a sales return
Sales Return Dr / Customer Cr
This is one reason correct account and transaction details matter when setting up your business in accounting software.
For example, when you record a sale, the software can update the customer’s balance, sales figures and applicable GST records based on the transaction.
With Vyapar, you can create invoices, record purchases and expenses, manage customer and supplier balances, track payments and view business reports from the same app. The accounting entries are handled in the background, so you don’t need to manually write every journal entry for routine transactions.
The golden rules of accounting become much easier once you stop trying to memorise every entry. With regular business transactions like sales, purchases, expenses, payments and GST, this logic becomes easier to follow.
And if you use accounting software such as Vyapar, you don’t need to manually write every debit and credit entry. You can focus on recording the transaction correctly while the accounting is handled in the background.
FAQs on the Golden Rules of Accounting
What are the three golden rules of accounting?
The three golden rules are:
Personal Account: Debit the receiver, credit the giver.
Real Account: Debit what comes in, credit what goes out.
Nominal Account: Debit all expenses and losses, credit all incomes and gains.
Is a bank account a personal account or a real account?
Under the traditional classification, a bank account is treated as an artificial personal account because a bank is a legal entity.
Is goodwill a real or nominal account?
Goodwill is treated as an intangible real account under the traditional classification.
Do the golden rules still apply when using accounting software?
Yes. Accounting software records the debit and credit entries in the background. You may not see or enter every journal entry manually, but the underlying accounting still follows the double-entry system.
Are drawings treated as an expense?
No. Drawings are the amount taken by the owner from the business for personal use. They reduce the owner’s capital rather than being treated as a business expense.
What is the difference between real and nominal accounts?
Real accounts are related to assets and generally carry their balances forward. Nominal accounts are related to income, expenses, gains and losses and are closed at the end of the financial year.
How are the golden rules used for GST?
GST collected on sales and eligible input GST on purchases are recorded separately from the sales or purchase value. The exact accounting treatment depends on the transaction and the applicable GST rules.
I’m a business enthusiast with 8+ years of experience in business management and finance, holding a Bachelor of Business Management (BBM) in Marketing and an MBA in Finance. With expertise in marketing, accounting, financial management, business law, MIS, and business economics, I focus on simplifying complex business and finance topics into clear, practical insights for entrepreneurs, professionals, and students.
- "Tax Professional & Business Finance Expert"
Introduction Retail businesses today need much more than basic bookkeeping. Between GST compliance, inventory valuation, expense tracking, profit monitoring, vendor payments, and daily sales reconciliation, managing finances has become increasingly complex.. To help retailers choose the right solution, I’ve compared five of the most popular accounting software options in India based on ease of use,…
Introduction Running a small business in India in 2026 means going through GST returns, e-invoicing, e-way bills, inventory, and daily bookkeeping, usually without a full-time accountant. The right GST accounting software for small business automates the heavy lifting and frees you to focus on growth. We’ve compared the five most widely used names in India,…
KEY TAKEAWAYS Form 16 is a TDS certificate issued by your employer showing salary income and tax deducted during the financial year It has two parts: Part A (TDS summary) and Part B (detailed salary breakup and deductions) Employers must issue Form 16 by 15 June after the end of the financial year You can…